Life coverage
Term and permanent structures designed to replace income, settle debts, and fund education if the unexpected happens.
Explore life benefitstherealcheftig insurance brings together personal and commercial lines so you can review limits, deductibles, and renewal paths in one conversation. Whether you are insuring a first home, adding a teenage driver, or expanding a storefront, our advisors translate policy language into decisions you can act on before the next renewal date arrives.
Meet our advisorsOur portfolio focuses on the five coverage types families and owners ask about most often. Each card below links to a service overview; your advisor can bundle lines when carriers allow multi-policy credits.
Term and permanent structures designed to replace income, settle debts, and fund education if the unexpected happens.
Explore life benefits
Individual and small-group medical plans with clear networks, out-of-pocket caps, and wellness incentives.
Health service detail
Dwelling, contents, and liability limits aligned to rebuild costs—not outdated purchase prices.
Home coverage overview
Liability, collision, and comprehensive options for commuters, rideshare drivers, and fleet owners.
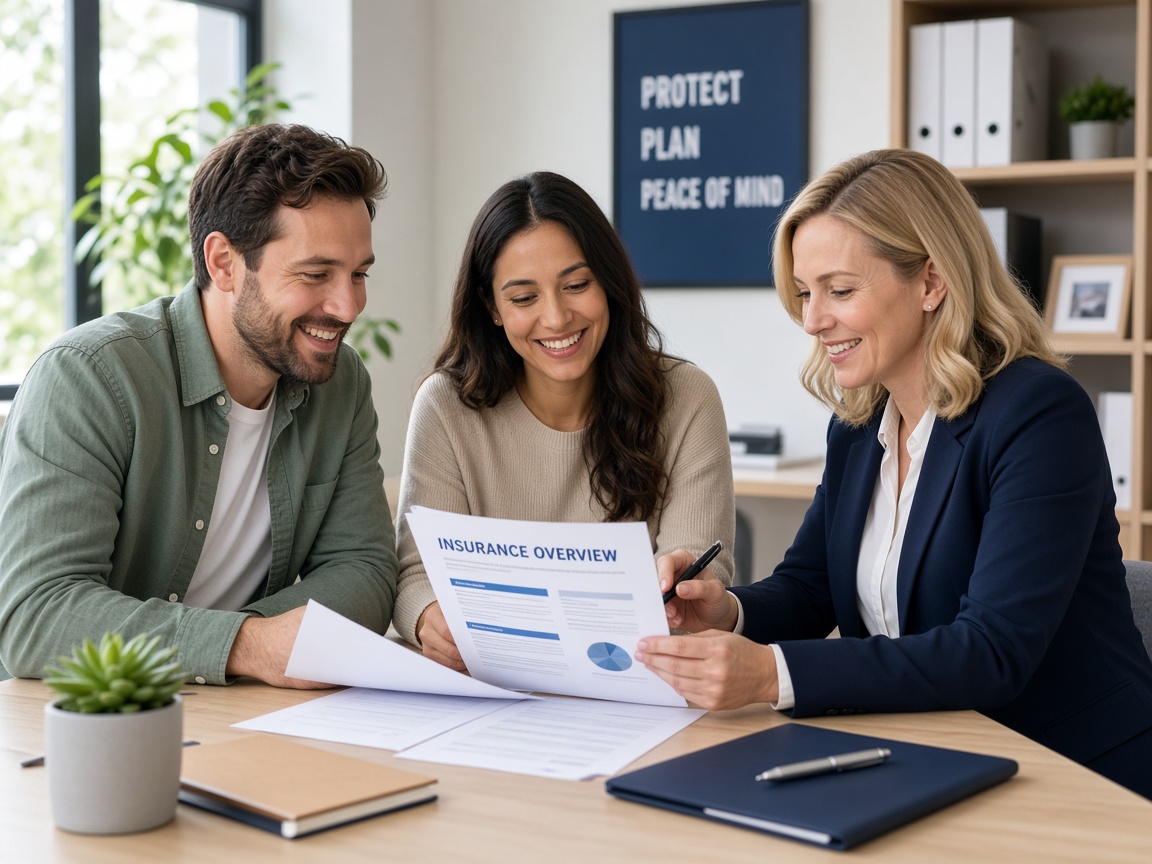
Auto coverage overviewInsurance contracts are long because risks are complex. We do not ask you to skim twenty pages alone. therealcheftig insurance pairs every quote with a plain-language summary of exclusions, waiting periods, and claim notification rules. That summary becomes your checklist when life changes—marriage, a home renovation, hiring staff, or adding a vehicle.
Our process starts with listening. We capture how you use your property, who depends on your income, and whether your business carries inventory or client data. Only then do we match carriers whose appetite fits your profile. You receive side-by-side comparisons instead of a single take-it-or-leave-it offer.
When a claim arises, the same team that sold the policy helps you gather proof of loss, photos, and receipts. We stay in the conversation until the carrier issues a decision, because continuity reduces stress when you already have enough on your mind.
“After a kitchen fire we feared our limits were too low. Our advisor walked us through the dwelling endorsement and the adjuster approved rebuild costs within two weeks.”
— Home policyholder, multi-line client
“Adding three delivery vans used to mean three separate binders. therealcheftig consolidated auto and general liability so our certificates update once.”
— Retail operator, commercial auto
“The health enrollment call covered specialist referrals and out-of-network math. We picked a plan knowing exactly what our chronic care would cost.”
— Small-group employer, health line
Every relationship is staffed by a named agent and a backup during peak season. Portraits below introduce the people answering your renewal questions.
Term lengths from ten to thirty years with optional riders for disability and critical illness. Enter your details to receive a preliminary premium range.
We estimate dwelling limits using rebuild guides and local construction indexes. Detached structures and flood endorsements can be added after the first pass.
Liability limits, uninsured motorist protection, and comprehensive deductibles are quoted together so you can see the full premium picture.
Replacement cost pays to rebuild or repair with materials of similar kind and quality without deducting depreciation. Actual cash value subtracts wear and tear, which can leave a gap after a major loss. We model both scenarios when you choose dwelling limits.
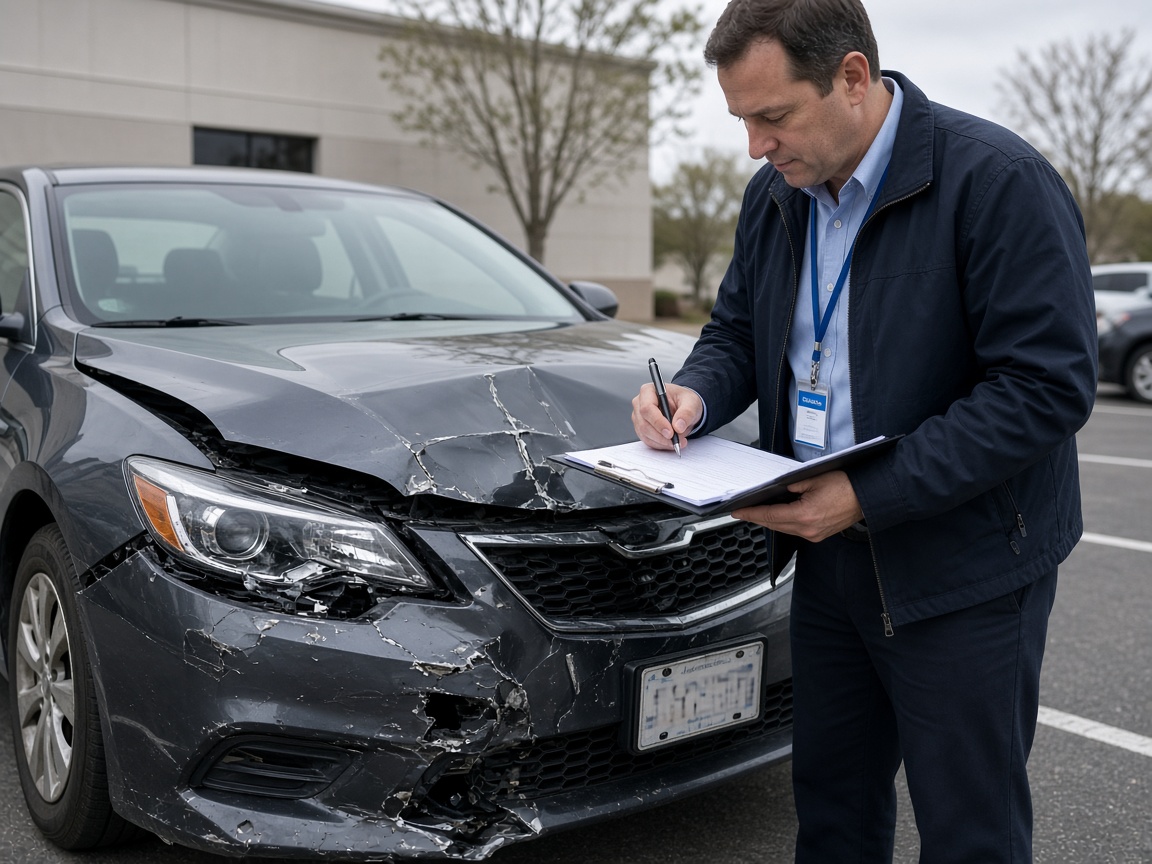
Notify us as soon as you are safe. Prompt reports help preserve evidence, secure witness statements, and meet carrier notification windows. We collect photos, police report numbers, and rental needs in one call.
Standard general liability focuses on bodily injury and property damage. Cyber endorsements add breach response, notification costs, and forensic support. We align limits with contracts your clients require.
Most policies activate after underwriting approval and first premium payment. Temporary binding may be available when exams are pending; your advisor confirms dates on the offer sheet.
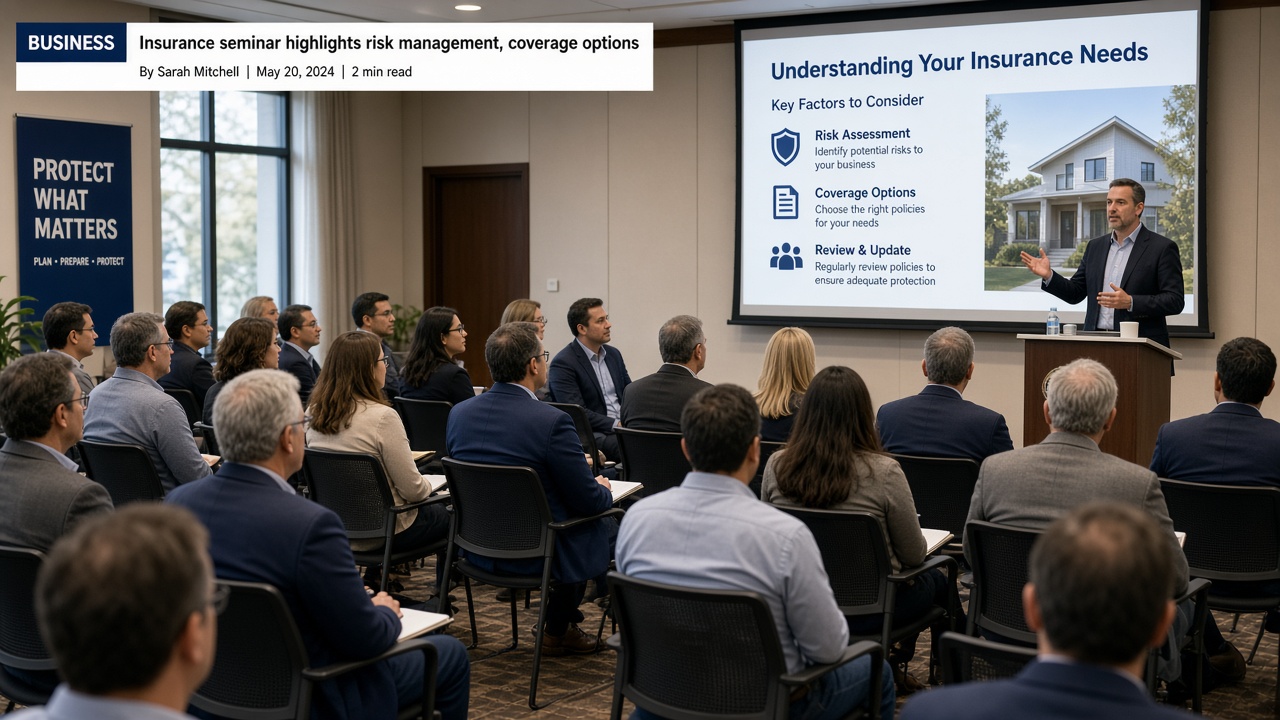
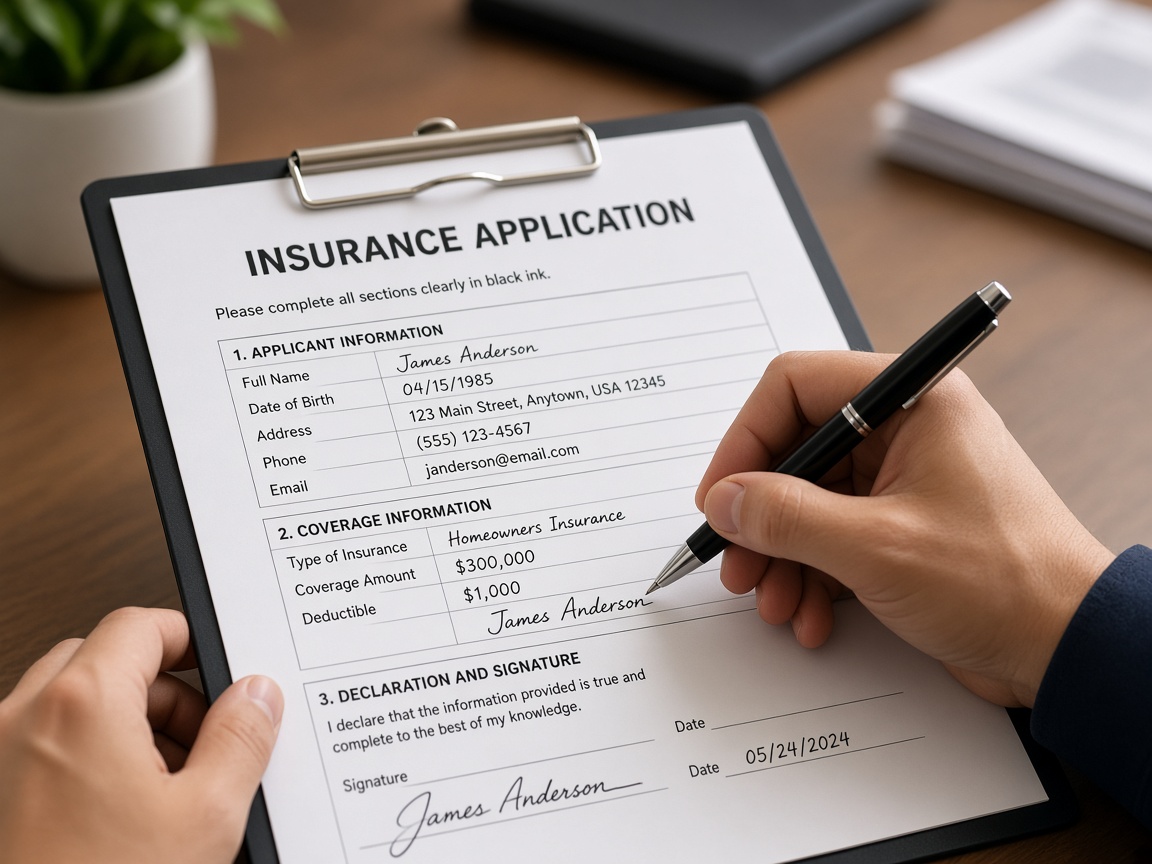
Learn which boxes control your premium, which limits bind at renewal, and where additional insured endorsements appear.
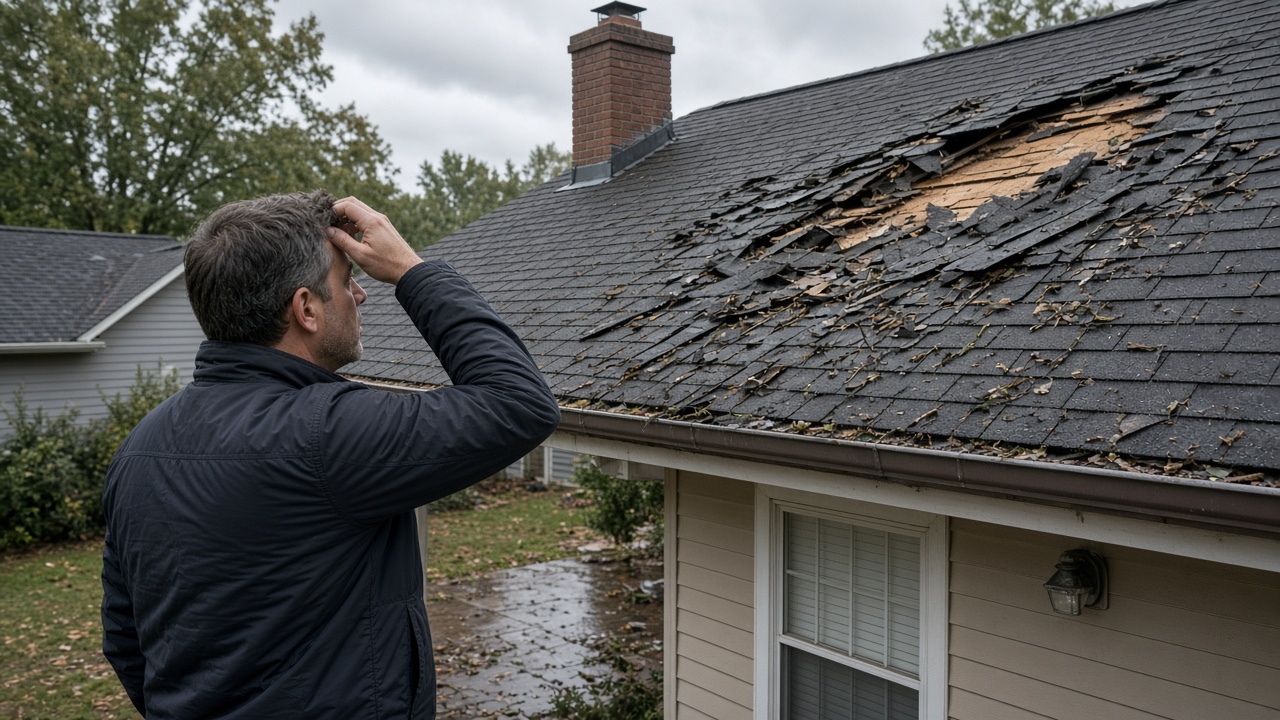
Document roofs, trim trees, and verify drainage before wind and hail arrive so claims start with solid evidence.
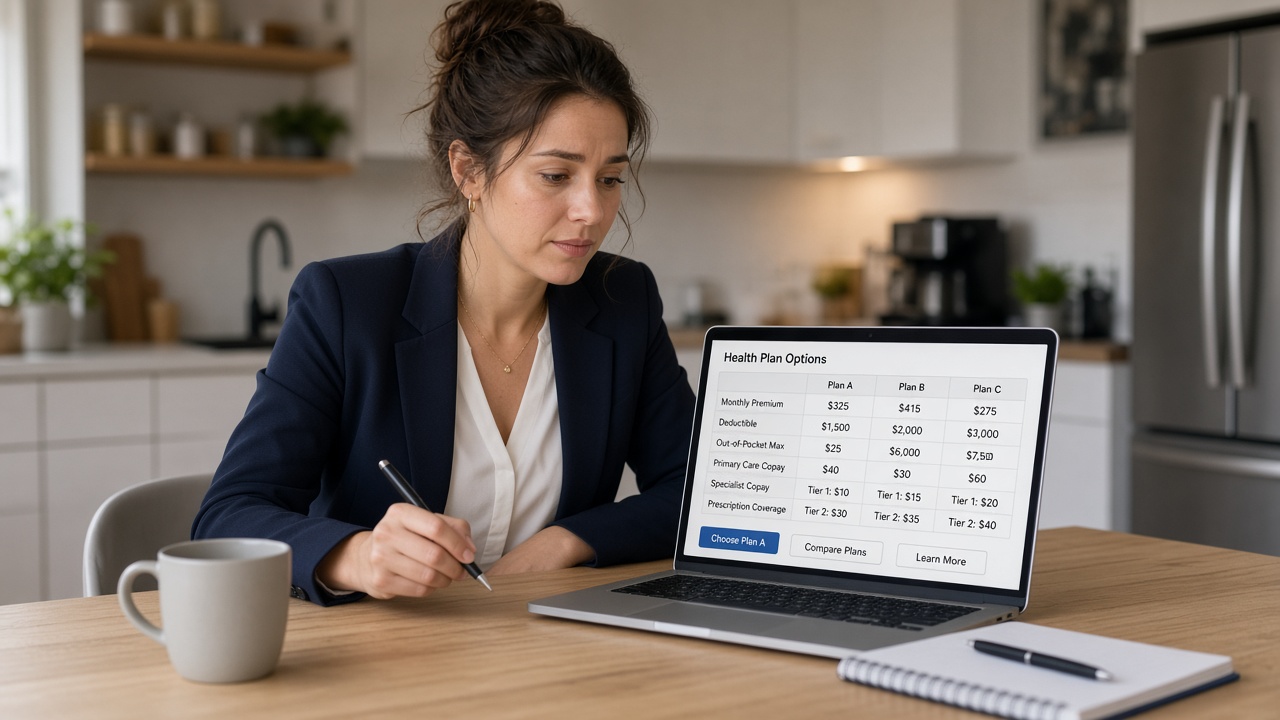
Compare network changes, pharmacy tiers, and contribution strategies before employees enroll for the next plan year.